The Regulation That Rewrote Catalogues
Euro 5+ — formally Stage 5+ under Regulation (EU) No 168/2013 as applied to L-category vehicles — came into force for new type approvals in January 2024, with sell-through provisions expiring for most categories shortly after. The headline change was not in raw emissions limits, which remained close to those set by Euro 5 in 2020, but in the on-board diagnostics requirements: OBD Stage II demanded continuous catalyst monitoring, throttle-position cross-referencing, and fault-code coverage that Euro 5's looser OBD Stage I never required. That shift in electronics architecture is where the product casualties accumulated.
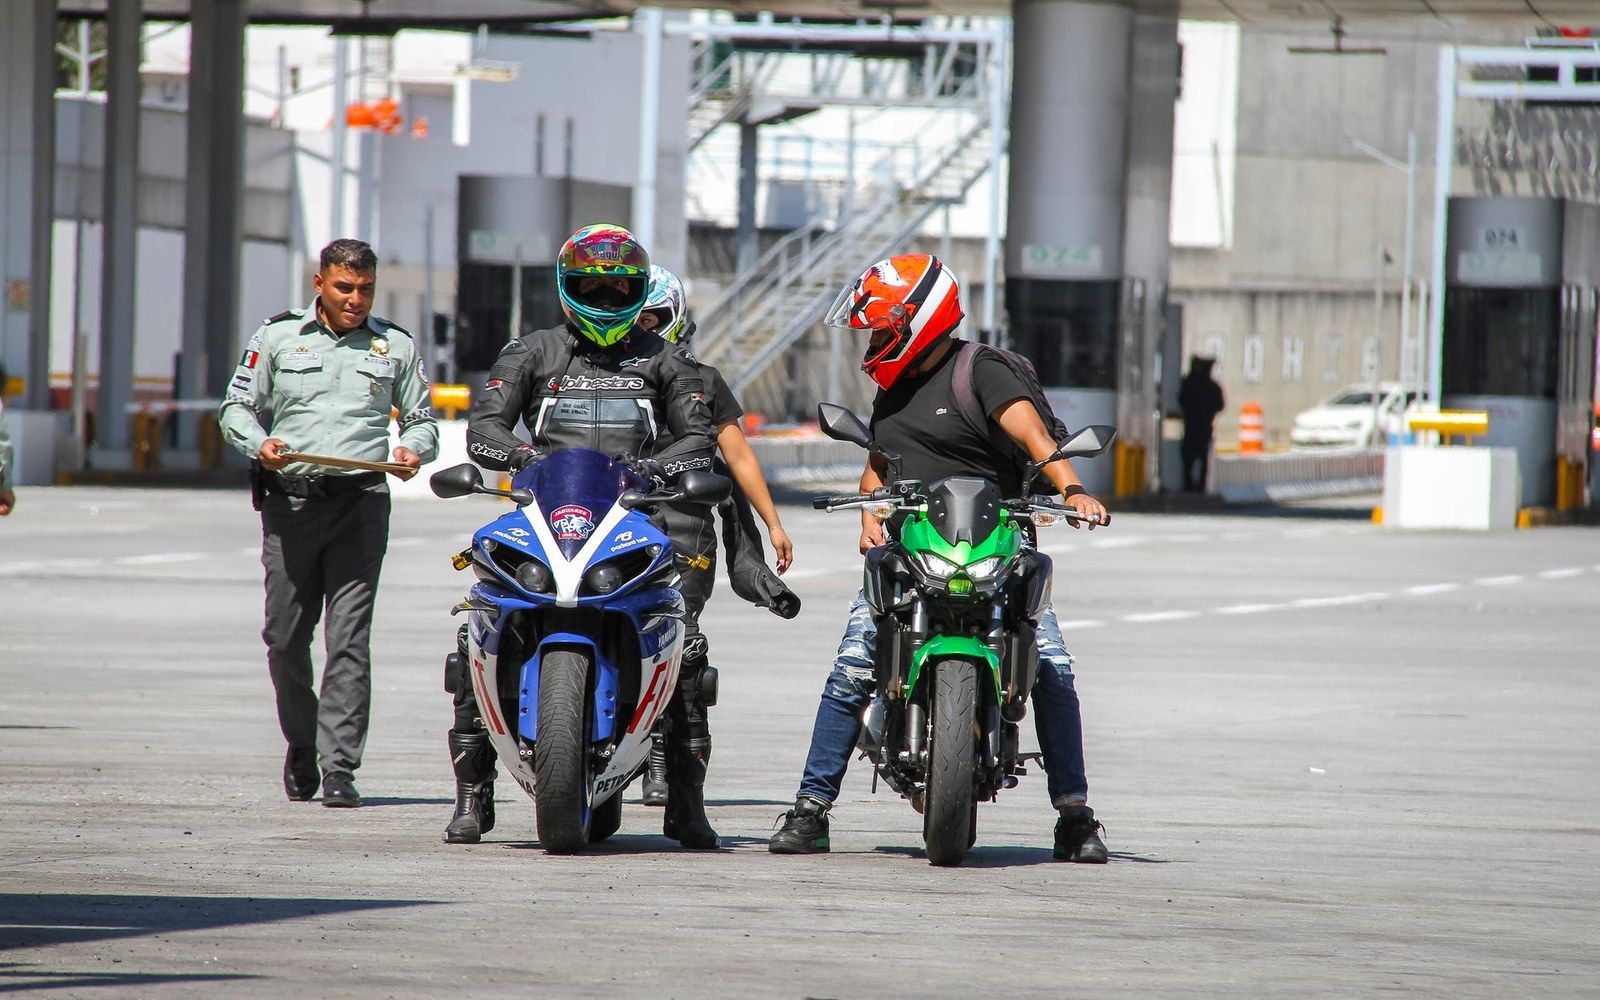
The costs fell hardest on carbureted and lightly electronified engines at the affordable end of the market and on low-volume speciality machines whose development amortisation could not absorb a full ECU and sensor package. Triumph updated its Bonneville line ahead of the 2024 deadline, with the T120 already carrying the more thoroughly instrumented electronics. Honda withdrew the CB300R from several European markets rather than certify a new OBD-II-compliant variant of the engine. Kawasaki quietly ended European sales of the Z400 in the same cycle. None of these decisions were announced as regulatory casualties; they appeared in distributor price lists as deletions, confirmed only when press offices acknowledged the standard as the proximate cause.
At the larger-displacement end, the reconfiguration was more surgical. BMW Motorrad re-homologated the R 1250 GS line with updated lambda-sensor mapping and additional OBD fault paths, absorbing the cost across a platform that already carried substantial electronics. Ducati similarly updated the Multistrada V4 and Panigale families without publicly disclosing the engineering expenditure, folding the OBD work into model-year refreshes. The Association des Constructeurs Européens de Motocycles had argued in its 2021 submission to the European Commission that OBD Stage II costs were disproportionate below the 300cc threshold, a position the Commission noted but did not act on.
The aggregate effect is a compression of entry-level European model diversity. The mid-displacement segment below 400cc, where Royal Enfield, KTM, and several Chinese manufacturers had expanded most aggressively under Euro 5, now carries a higher floor cost per unit that disadvantages short production runs and single-market introductions. The regulation text itself is published by the European Commission in EUR-Lex ↗ and the OBD obligations are detailed in the delegated regulation amendments adopted in 2022. Manufacturers filing new type-approval applications in 2025 are working to that baseline; the models that did not survive the transition are, by definition, absent from those filings.